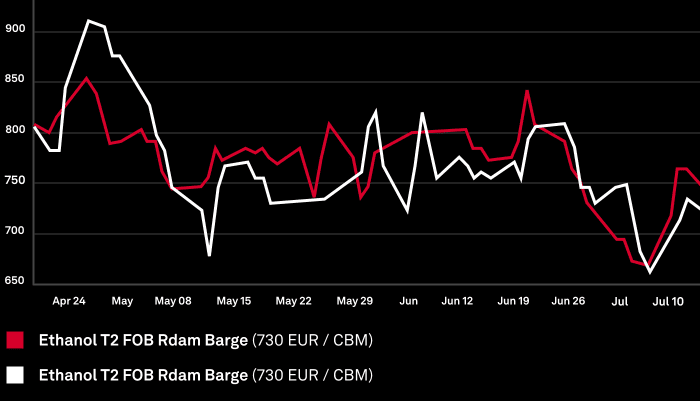
Renewable diesel outright prices in Northwest Europe saw losses in the week ended Oct. 7, with traders widely reporting sellers in the ARA hub to be under pressure owing to a build-up in supply, while German compliance demand remains shut out due to low Rhine water levels.
Platts assessed the RD-A FOB FARAG outright price at $3,268.25/mt on Oct. 7, down 4.6%, or $158.50/mt, week-over-week. Likewise, the RD-B outright was assessed at $2,902.75/mt, down 4.5%, or $136.75/mt, on the week, resulting in a $365.50/mt spread between the two products.
In the underlying diesel markets, Platts assessed the FOB ARA ULSD Barge price at $1,408.50/mt on Oct. 7, down 3.5%, or $50.50/mt, week-over-week, despite an $86.25/mt rally during the Oct. 7 trading session amid reports of renewed attacks on vessel transits in the Strait of Hormuz.
Broadly, the underlying ULSD market has softened over the past trading week in line with bearish sentiment for gasoil futures.
The G7’s announcement Oct. 2 that it would release 100 million barrels of oil stocks over the next four months, alongside market chatter surrounding a potential easing of Russia’s diesel export ban, have both contributed to softer European diesel prices, weighing in turn on renewable diesel outright prices.
Renewable diesel premiums also softened over the week, defying their typical inverse relationship with the underlying diesel contract.
Market sources had been reporting for several weeks that diesel and renewable diesel fundamentals have become “decoupled” owing to RD’s inherent value in meeting RED III compliance obligations, alongside the impact of the Rhine on supply and demand fundamentals.
“Premiums on RD seem to be very independent from gasoil,” a Germany-based fuel supplier said.
Platts assessed the RD-A premium to Platts ULSD FOB Barges at $1,359/cu m on Oct. 7, down 5.6%, or $81/cu m, week-over-week. Similarly, the RD-B premium was assessed 5.6% lower on the week, settling at $1,074/cu m.
In previous weeks, Platts heard from market sources that advanced RD premiums were holding relatively rangebound despite volatility in the underlying diesel markets, due to the bullish outlook for RD given how essential it is for meeting RED III obligations.
The prevailing view in the market is that RD blending in the fourth quarter will need to drastically step up for obligated German parties to meet their compliance obligations under RED III.
That deadlock appears to have shifted over the last week, with sources reporting that sellers in ARA are under pressure to offload volumes due to a build-up in supply.
“There is too much [RD volume] in ARA and not enough of it can go down the Rhine,” the fuel supplier said, adding that premiums could continue to be pressured unless another outlet for the glut of supply in ARA is found. “There are more volumes planned before the end of the year.”
A second trader echoed the sentiment, saying “[sellers] can’t keep storing forever – it's financially punitive because of the backwardation, plus they have scheduled deliveries coming in and they don’t have unlimited storage capabilities.”
With Rhine water levels continuing to linger near record lows, it remains unclear what the potential outlets for RD supply are in the near term, with market sources having previously reported Dutch demand to be relatively weak, while trucking and rail solutions into the German market were also heard to be operating at full capacity.
Data from inland navigation agency WSV showed Rhine water levels at the Kaub gauge measuring 3 cm on Oct. 8.
German compliance tickets, or THG-Other, were assessed at Eur494.75/mtCO2e Oct. 7, down Eur15.25/mtCO2e, or 3%, week-over-week, tracking losses witnessed for physical RD.
This said, sources noted that the compliance value of tickets remains significantly elevated relative to physical renewable diesel’s compliance value, thus meaning that now is a profitable time for German parties to blend physical RD and sell the corresponding tickets should they have blending infrastructure that is unaffected by the Rhine water levels.
However, some sources have questioned how much HVO volume could be blended before jeopardizing the EN590 fuel quality standards on density, given that HVO is a lighter product than diesel.
Platts is part of S&P Global Energy.
California and US Gulf Coast renewable diesel outright prices edged down in the week ended Oct. 7.
Platts, part of S&P Global Energy, assessed the Los Angeles RD (99%) price with CCA at 472.27 cents/gallon on Oct. 7, down 1.93% week over week. RD Los Angeles-to-San Francisco differential widened to 7.75 cents/gal. Platts assessed RD99 FOB USGC at 467.77 cents/gal, down 1.33% week over week. The San Francisco RD (99%) ended the week down 1.65%, at 480.02 cents/gal.
Both tallow and soybean oil margin indicators increased week over week.
US RD margin indicator for tallow increased by 16.48 cents to 425.41 cents/gal, despite tallow remaining unchanged at 65.50 cents/pound.
The US RD soybean oil indicator also increased to 360.14 cents/gal, up 5.68% from the previous week, amid soybean futures falling.
The front-month Chicago Board of Trade soybean oil futures contract slightly decreased to 67.42 cents/pound, down by 0.63% from the previous week.
During the week, current-year D4 RINs increased by 1.83% week over week. Renewable diesel generates 1.70 D4 RINs/gal; therefore, renewable diesel producers can claim $3.5445/gal.
The RD margin indicator measures margins for RD production. A higher margin indicator encourages RD producers to maximize production.
As the RD margin indicator decreases, the cost of producing RD rises, leading to weaker overall blending economics and unfavorable margins. This could occur due to higher feedstock soybean oil or tallow prices, lower blendstock heating oil prices, or a drop in the value of credits.
The RD soybean margin indicator is calculated by adding the cost per gallon of heating oil to the value of credits -- clean fuel production credit, low-carbon fuel standard, and RINs -- and then subtracting the product of the cost per pound of soybean oil multiplied by 8.5, which is the yield for RD.
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,200/cu m, via OLYX; 15:10:58.055 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,150/cu m, via OLYX; 15:10:51.134 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $950/cu m, via OLYX; 15:10:46.744 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $900/cu m, via OLYX; 15:10:39.983 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,325/cu m, via OLYX; 15:16:35.204 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,250/cu m, via OLYX; 15:16:29.763 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,025/cu m, via OLYX; 15:16:24.091 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $925/cu m, via OLYX; 15:16:18.588 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,375/cu m, via OLYX; 15:17:08.162 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,275/cu m, via OLYX; 15:17:01.378 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,075/cu m, via OLYX; 15:16:48.593 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $950/cu m, via OLYX; 15:16:40.665 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, offer corroborated at $1,360/cu m; 14:59:47.782 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, offer at $1,360/cu m; 14:31:50.300 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,425/cu m, via OLYX; 15:07:18.127 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,350/cu m, via OLYX; 15:07:13.180 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,150/cu m, via OLYX; 15:07:08.398 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,050/cu m, via OLYX; 15:07:02.333 GMT
~~ Platts RD: RD-A: Spot, Blue-PoS, FOB ARA, 1kt, min 85% GHG savings, premium to ICE gasoil, trade at $1,200/cu m; 15:06:57.211 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,475/cu m, via OLYX; 15:06:38.806 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,375/cu m, via OLYX; 15:06:16.439 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative offer at $1,150/cu m, via OLYX; 15:06:07.372 GMT
~~ Platts RD: RD-B: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, indicative bid at $1,050/cu m, via OLYX; 15:05:58.493 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, offer at $1,400/cu m; 14:32:50.973 GMT
~~ Platts RD: RD-A: Spot, FOB ARA, 1kt, min 85% GHG savings, premium to Platts ULSD, bid at $1,360/cu m; 14:29:52.960 GMT